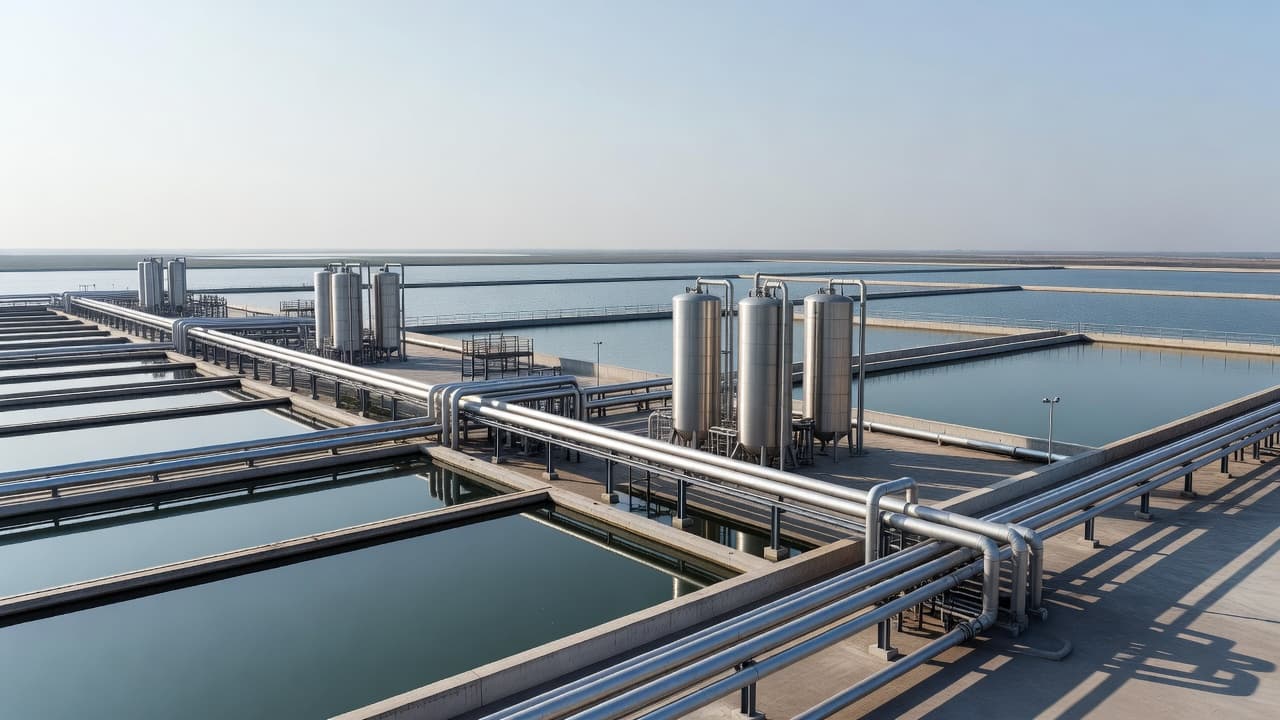
Global water infrastructure is entering a long term expansion cycle that will define chemical demand through 2035. The water treatment chemicals demand drivers are becoming more complex as urbanisation, industrial regulation and high technology infrastructure converge into a single consumption ecosystem.
The global water treatment chemicals market is projected to grow from USD 40.2 billion in 2025 to USD 48 billion by 2030 at a 4.5% CAGR. Wastewater treatment chemicals are expected to reach USD 64.9 billion by 2033, while decentralised treatment systems expand at around 7% CAGR to USD 2.83 billion by 2035.
This growth is not uniform. It is driven by structural shifts in water availability, regulatory enforcement and industrial water reuse requirements.
Urbanisation pressure driving municipal water treatment expansion
Urbanisation remains the most powerful structural driver of water treatment chemical demand. Rapid population growth in Asia and Africa is increasing pressure on municipal water systems that require continuous chemical treatment support.
Cities are expanding faster than water infrastructure upgrades in many regions, creating long term dependency on chemical based treatment systems.
Key urbanisation drivers include:
Expansion of megacities in India, Southeast Asia and Africa
Rising per capita water consumption linked to industrialisation
Aging water infrastructure in developed economies requiring rehabilitation
Municipal systems rely heavily on continuous dosing of treatment chemicals to maintain water quality standards. This creates stable baseline demand regardless of economic cycles.
Chemical usage is concentrated in:
Disinfection systems for potable water
Coagulation and flocculation processes for suspended solids removal
pH adjustment and stabilisation systems
Urbanisation ensures that water treatment chemicals remain a foundational industrial segment through 2035.
National water security programs shaping long term chemical demand
Government-led water security initiatives are significantly accelerating demand for treatment chemicals. Large scale infrastructure programs in India and China are especially influential in shaping global consumption patterns.
Jal Jeevan Mission is one of the largest rural water supply initiatives globally, targeting universal household tap water access. This program requires extensive deployment of disinfection, filtration and distribution treatment systems.
China Water Ten Plan focuses on improving water quality, reducing industrial discharge and upgrading municipal wastewater systems.
These initiatives drive demand through:
Large scale expansion of water treatment plants
Continuous chemical dosing requirements for distributed systems
Industrial compliance upgrades across manufacturing zones
Policy driven demand creates predictable long term consumption patterns, making government programs a key stabilising factor for chemical suppliers.
Industrial wastewater regulation tightening across global manufacturing hubs
Industrial wastewater treatment is becoming a central regulatory focus across global manufacturing economies. Governments are tightening discharge standards, forcing industries to invest in advanced chemical treatment systems.
The wastewater treatment chemicals market is projected to reach USD 64.9 billion by 2033, driven largely by industrial compliance requirements.
Key regulatory trends include:
Stricter effluent discharge limits for heavy industries
Mandatory reuse of treated water in water stressed regions
Higher penalties for non compliance in manufacturing zones
Industries with high water intensity include textiles, chemicals, mining and power generation. These sectors require continuous chemical treatment to meet discharge standards.
Critical chemical categories include:
Coagulants and flocculants for suspended solids removal
Biocides for microbial control in wastewater systems
Oxidising agents for organic contaminant breakdown
Industrial regulation converts water treatment chemicals from optional inputs into mandatory operational costs.
Zero liquid discharge systems reshaping chemical intensity in water treatment
Zero liquid discharge (ZLD) systems are becoming a major driver of chemical demand in water stressed regions. These systems aim to eliminate liquid waste by recovering and recycling nearly all process water.
ZLD systems require significantly higher chemical usage compared to conventional treatment systems.
Key drivers of ZLD expansion:
Severe water scarcity in industrial zones
Government mandates in high stress regions
Corporate sustainability commitments on water reuse
Chemical demand increases due to:
Multiple stage filtration and precipitation processes
High dosage requirements for contaminant removal
Concentration of salts and heavy metals requiring advanced treatment
This results in significantly higher consumption of coagulants, flocculants and scaling control chemicals per unit of water treated.
ZLD adoption is especially strong in textiles, power plants and chemical manufacturing clusters.
AI data centers creating a new high purity water chemistry segment
One of the most unexpected demand drivers for water treatment chemicals is the rapid expansion of AI data centers. These facilities require ultra pure water systems for cooling and chip related processes.
As rack densities increase, liquid cooling systems depend heavily on water purity and stability. Even minor ionic contamination can damage sensitive electronic systems.
Water treatment requirements in data centers include:
Deionisation systems for ultra pure water loops
Corrosion inhibitors for closed cooling circuits
Biocides to prevent microbial growth in recirculating systems
This creates a new category of industrial water chemistry that sits between electronics manufacturing and traditional water treatment.
Demand growth is linked directly to:
Expansion of global data center capacity
Rising AI compute density requirements
Shift from air cooling to liquid cooling systems

Core chemical segments driving water treatment growth
Water treatment chemistry is built on a stable set of core chemical categories that remain essential across municipal, industrial and high tech applications.
Key demand segments include:
Coagulants for particle aggregation and sedimentation
Flocculants for suspended solids removal
Biocides for microbial control in water systems
Corrosion inhibitors for pipeline and equipment protection
These chemicals form the backbone of both large scale municipal systems and decentralised treatment plants.
Decentralised wastewater systems expanding in emerging markets
Decentralised wastewater treatment is emerging as a fast growing segment with a projected CAGR of 7% through 2035. This model supports small scale treatment systems closer to the point of use.
Growth is driven by:
Rapid urban expansion outpacing central infrastructure
Industrial clusters requiring localized treatment systems
Rural and semi urban water access expansion
These systems rely on modular chemical dosing solutions that are easier to deploy and maintain compared to large centralised plants.
Key advantages include:
Lower infrastructure investment requirements
Faster deployment timelines
Flexibility in scaling capacity
This segment is particularly relevant in emerging economies where infrastructure expansion must keep pace with population growth.
Supply chain and procurement challenges in water treatment chemicals
Water treatment chemical procurement is becoming more complex due to regulatory fragmentation and regional water stress conditions.
Key challenges include:
Variability in discharge standards across regions
Seasonal demand fluctuations linked to water availability
Increasing demand for higher purity chemical grades
Procurement teams must also manage supply continuity risks in critical infrastructure sectors where downtime is not acceptable.
Additional challenges include:
Transportation costs for bulk liquid chemicals
Storage stability for oxidising agents and biocides
Supplier qualification for high compliance applications
Supply chain resilience is becoming as important as pricing efficiency in this sector.

Market outlook for water treatment chemicals through 2035
The long term outlook for water treatment chemicals remains structurally positive due to persistent global water stress and regulatory expansion.
Growth will be supported by:
Continuous urbanisation in developing regions
Expansion of industrial wastewater regulations
Rising adoption of water reuse and ZLD systems
New demand from AI and high tech infrastructure
At the same time, innovation in treatment technologies will increase chemical efficiency but not reduce overall demand due to expanding water treatment coverage.
The sector will remain one of the most stable chemical demand categories due to its essential infrastructure nature.

What buyers should do to prepare for long term water chemical demand
Procurement strategies must adapt to a structurally expanding and increasingly regulated market. Water treatment chemicals are shifting from commodity procurement to critical infrastructure sourcing.
Key actions include:
Securing long term supply agreements for coagulants and flocculants
Diversifying suppliers across regional manufacturing hubs
Aligning procurement with regulatory compliance cycles
Preparing for higher purity requirements in industrial and digital sectors
Buyers must also anticipate rising chemical intensity per unit of water treated as reuse and ZLD adoption expands.
Ready to source Polyaluminium Chloride - China from verified global suppliers? Explore competitive offers on our platform today.
Polyaluminium Chloride CAS: 1327-41-9