Related Insights
Food Ingredient Logistics: Cape Routing BAF Reset and What July Freight Relief Looks Like
The July 1 bunker adjustment factor reset marks the first measurable freight cost relief for food ingredient buyers since the 2026 shipping crisis began. Procurement teams importing under CIF or CFR terms should use this week’s freight surcharge reduction as leverage to renegotiate H2 supplier pricing.
July BAF Reset: How Lower Brent Crude Cuts Cape Shipping Costs
The first major monthly bunker adjustment factor reset of 2026 reflects Brent’s fall to $73.05, delivering a tangible freight cost cut for Cape of Good Hope routes. Chemical shippers can expect a 10‑20% drop in Cape surcharges, translating to $150‑$350 per TEU on major legs. It’s a partial relief, but a crucial lever for Q3 contract talks.
The Nine Major Carriers' Hormuz Posture: Where Each Stands on July 1
The world's nine largest container shipping lines continue maintaining Cape of Good Hope routing as their operational standard entering H2 2026. For chemical buyers shipping under CIF and CFR contracts, understanding each carrier's operating posture is now a critical component of logistics and insurance planning.
485 Vessels Still Anchored: What the Gulf Shipping Backlog Means for Chemical Logistics in H2 2026
Gulf exports have recovered significantly during H1 2026, yet hundreds of vessels remain anchored across the region. This backlog highlights why chemical buyers should expect a gradual logistics recovery rather than an immediate return to normal shipping conditions.
Soda Ash Freight Costs Fall as Lower Brent Prices Open New Buying Opportunities
Falling Brent crude prices are reducing shipping cost pressure across global soda ash trade routes. This analysis explains how lower bunker fuel costs could improve contract negotiations for glass, detergent and water treatment buyers.
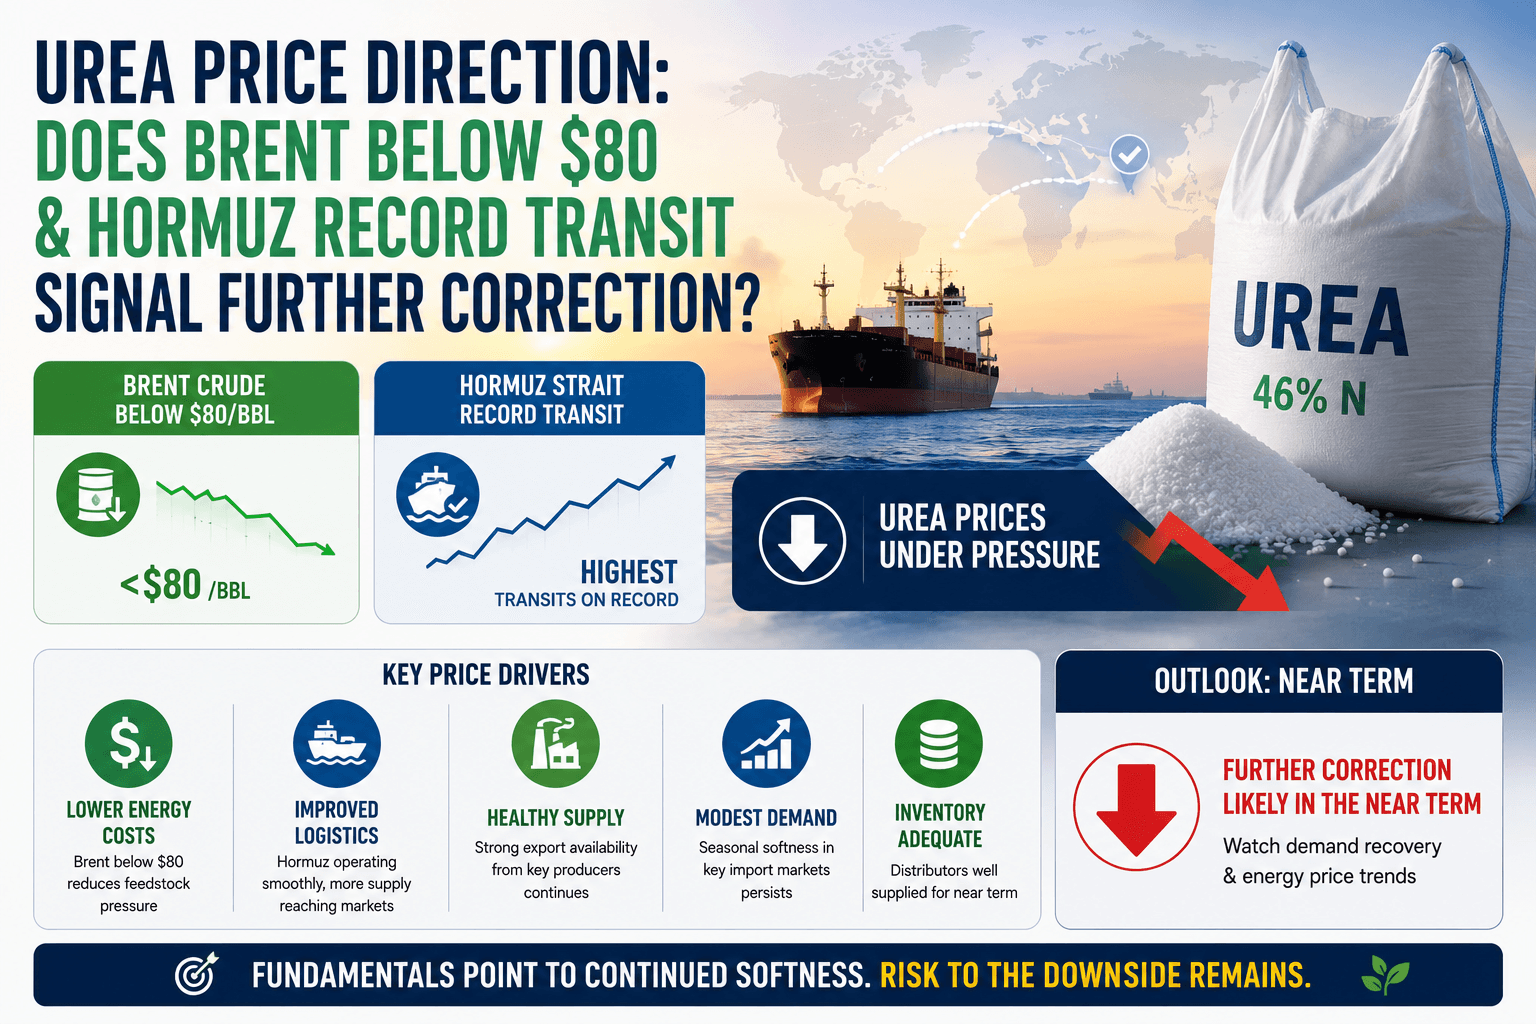
Urea Price Direction: Does Brent Below $80 and Hormuz Record Transit Signal Further Correction?
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
Don't miss out on our updates! Subscribe to our newsletter now
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.