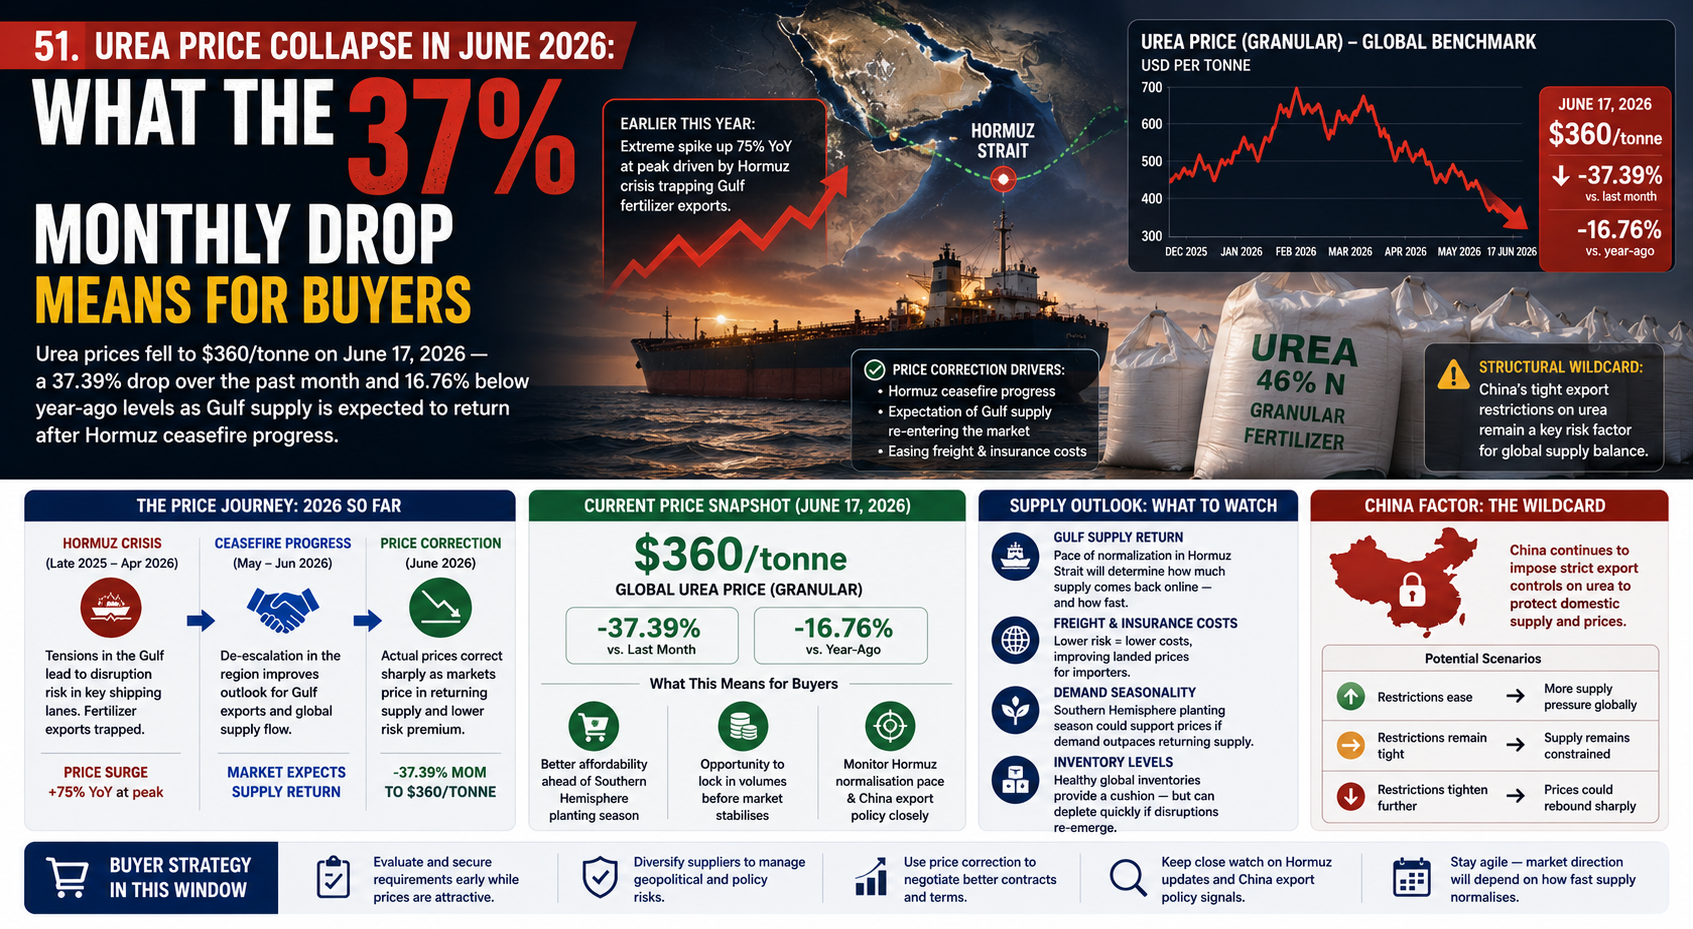
Urea (Granular) - Egypt CAS: 57-13-6
The global MSG market enters a critical procurement period as major Chinese producers prepare their second half of 2026 pricing. Freight costs have eased, feedstock conditions remain favorable and buyers have a limited window to secure competitive contracts before new price schedules take effect.
Gulf caustic soda supply is returning as Hormuz trade flows recover, creating new competition for Asian chemical suppliers. This analysis explains how buyers can prepare for changing pricing and sourcing options in Q3 2026.
The end of India’s fertilizer duty waiver and the launch of the MMTC Q3 tender are reshaping procurement strategies for urea and DAP. Farmers, importers and policy makers are recalibrating expectations as pricing volatility rises. This article dissects the key drivers and market implications.
Methanol markets have experienced some of the most severe disruptions during the Hormuz crisis due to their heavy dependence on Gulf export routes. As signs of supply normalization emerge after the Bürgenstock agreements, buyers and producers must reassess Q3 pricing expectations and procurement strategies.
The PE and PP market outlook for 2026 remains shaped by slow supply recovery, ongoing risk premiums and Gulf production constraints after Hormuz disruptions. Buyers should prepare for a longer normalization period instead of expecting immediate returns to pre-crisis pricing.
Strong exports from Belarus and Russia are helping stabilize potash markets despite ongoing fertilizer demand growth.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.