Urea (Granular) - Egypt CAS: 57-13-6
Urea (Granular) - Egypt CAS: 57-13-6
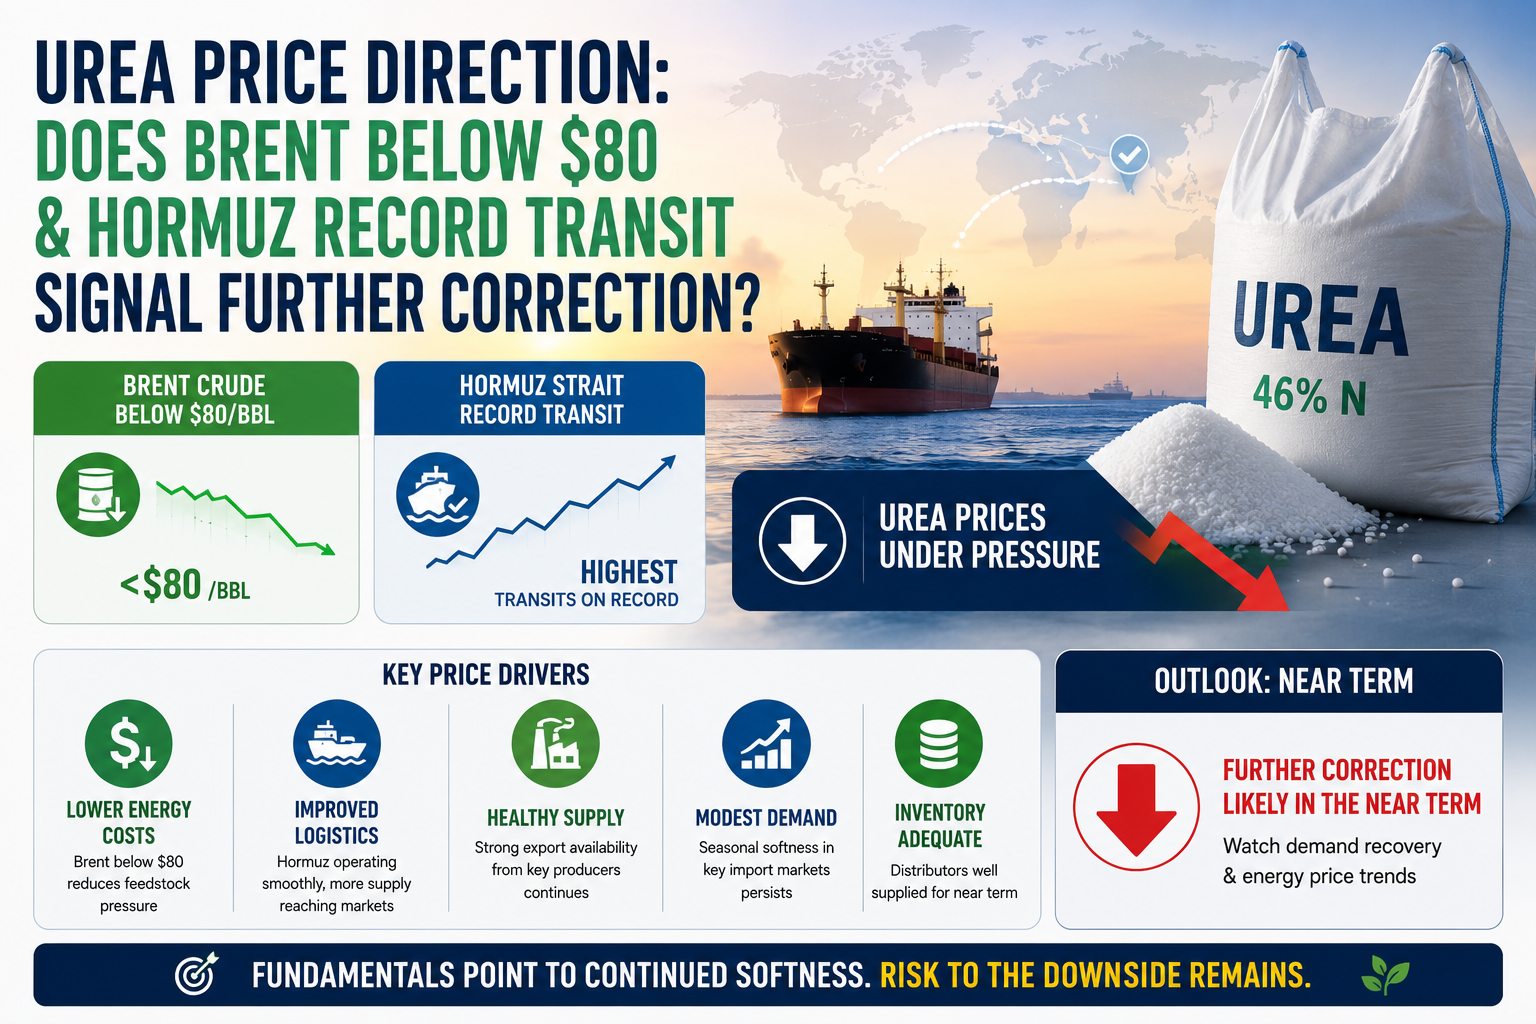
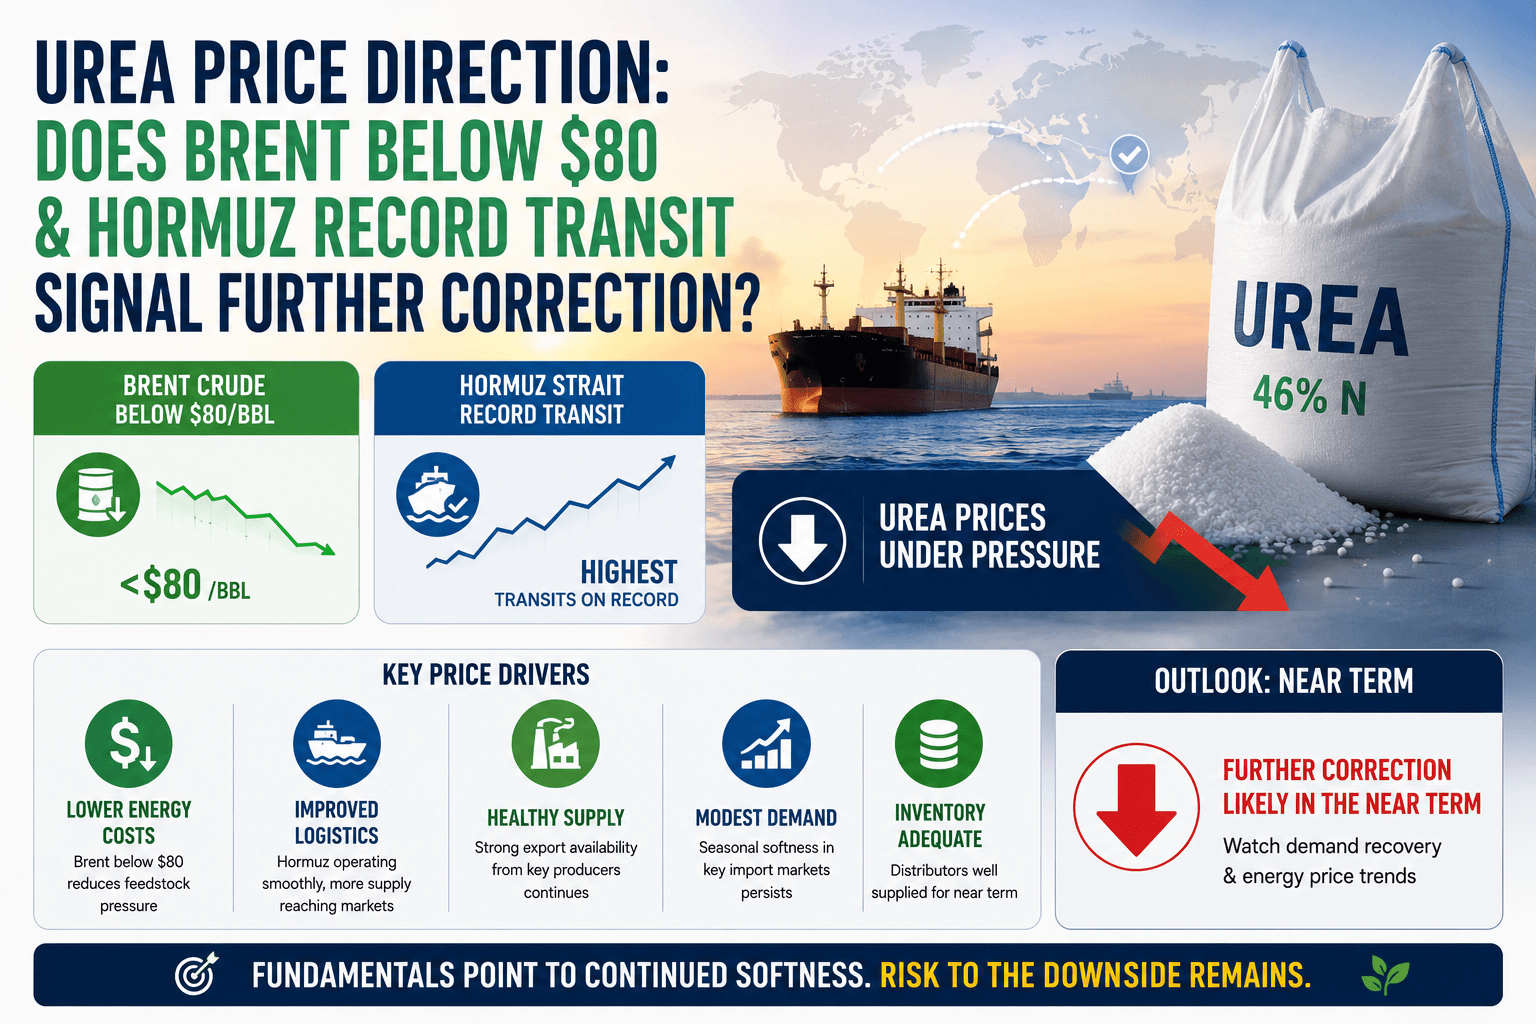
Urea prices in 2026 are poised for a rebound as Gulf exports climb back to 75% of pre‑war levels. This shift reshapes demand in the Southern Hemisphere, offering new buying windows for fertilizer importers. TradeAsia tracks the latest market dynamics for SABIC and QAFCO urea.
Lower crude prices are opening a cost correction window for coatings manufacturers sourcing solvents and resins.
Brent crude has dropped to $72.60 despite ongoing military escalation across the Gulf. This unusual market reaction signals that supply recovery currently outweighs geopolitical risk, creating important implications for petrochemical procurement and chemical pricing in the months ahead.
Saudi Arabia’s Ras Tanura restart is improving confidence in Gulf chemical logistics and methanol availability. This analysis explains how recovering supply, crude prices and shipping conditions could influence Q3 methanol procurement strategies.
Petrochemical markets are moving toward recovery as Brent prices ease, Hormuz transit improves and supply confidence returns. This outlook explains why price correction may happen slowly rather than through a sharp decline.
In 2026, the global NPK fertilizer market confronts steep cost hikes in nitrogen, phosphate and potash, tightening margins for blenders and buyers alike. Supply chain disruptions, regulatory shifts and volatile raw material prices are reshaping the industry’s economics.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.